
The Growth Navigator is a practice-oriented growth program by the Vienna Business Agency for startups that are already on the market and planning their next development step. It supports founding teams in setting strategic priorities, identifying growth barriers, and implementing concrete steps toward scaling. Founders can choose from four sprints, Product-Market Alignment, Sales & Go-to-Market, Investment & Financing, and Operational Excellence & Organisation, applying for all four or only the ones most relevant to their stage.
Konsultori contributes expert knowledge and program concept across all sprints, with one shared goal: help founders build the clarity, confidence, and strategic foundations that make growth sustainable.
For accelerator and program managers, Sprint 3 is a useful reference point: it shows what a structured, four-week investor readiness process looks like in practice, and what founders in your own cohorts might still be missing before their first real investor conversation.
Sprint 3: Investment & Financing
By the time founders reach Sprint 3, they usually carry two things: some traction, and a pitch deck they are quietly unsure about. Sprint 1 sharpened their product-market fit. Sprint 2 gave their sales pipeline structure and discipline. Now the question shifts again: are they actually ready to raise capital, or just ready to talk about it?
Sprint 3 is built around that distinction. Founders often assume investor readiness is a communication challenge, a matter of having the right slides and the right story. What they discover in this sprint is that it is an operational challenge first. A financial model, a pitch deck, and a CRM pipeline all have to say the same thing at the same time, and most founders have never been asked to make that true. Accelerators looking to build this kind of structure into their own cohorts can explore Konsultori’s Raising Money from Investors workshop.
Over the course of the sprint, participants build a targeted investor list, stress-test their financial model, and go through a due diligence style review before they ever sit in front of an actual investor.
Meet the Trainer
Petra Wolkenstein is CEO at Konsultori. She works with founders across all stages on strategy, product-market fit, sales, and investor readiness. In Sprint 3, Petra leads the Investor Process Introduction and the Investor Readiness review, focusing on data room preparation, outreach lists, and the shift from pitching a story to defending a business.
Investor Readiness: From Pitching to Pipeline
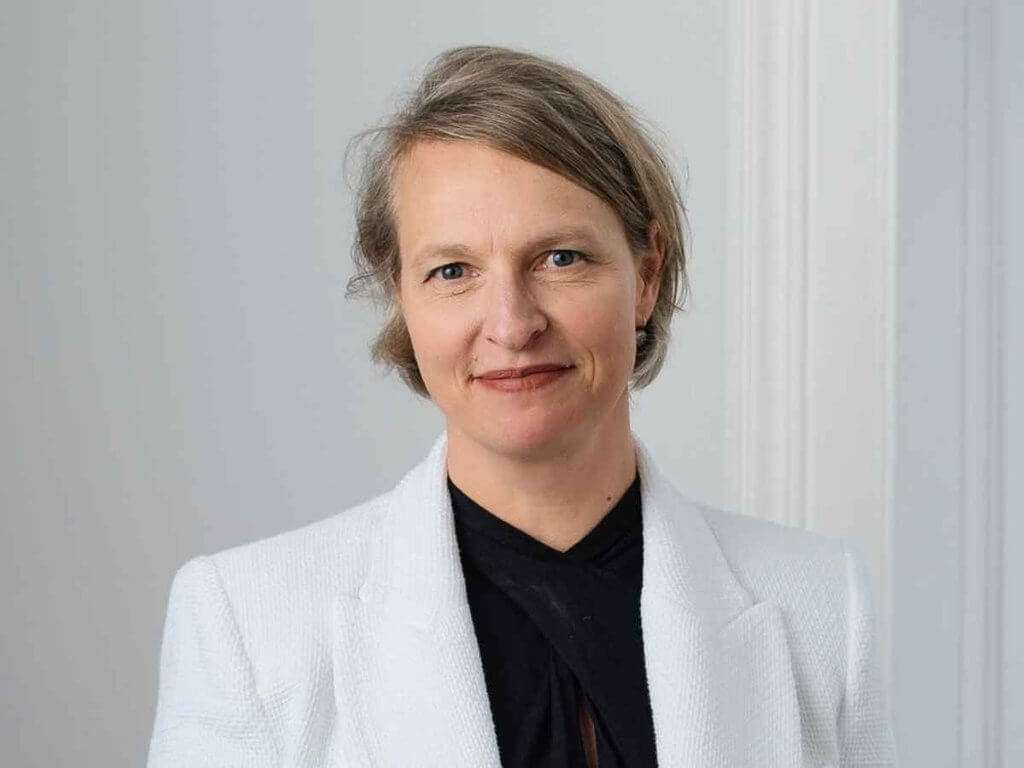
Interview with Petra Wolkenstein on what early-stage founders get wrong about raising capital
Most founders think investor readiness means having a great pitch deck. From your experience introducing founders to the investor process, what are the things they’re almost never prepared for, and why does that gap exist?
A great pitch deck is just an invitation to the conversation; it’s not the deal itself. The biggest gap I see is that founders view fundraising as a creative storytelling exercise, whereas investors treat it like a rigorous, high-stakes sales pipeline. Founders are almost never prepared for the operational depth and structural interdependencies required once an investor opens the hood.
In our program, we give founders 4 weeks between the sprint start and the final results review. What’s fascinating is seeing how founders handle that timeframe: roughly 40% of participants understand the assignment immediately, they reserve dedicated time on their calendars and work through it systematically. The other 60% start out thinking, “I can knock this out in a single afternoon.”
They quickly hit a wall. They realize that behind seemingly simple preparation tasks and prompts lies deep strategic work. Fundraising prep isn’t a quick checklist; it’s a sequential process where everything is interconnected. For example, on the revenue side alone, your financial plan, your pitch deck’s market assumptions, and your actual CRM pipeline status all have to speak to each other seamlessly. If one number changes in your financial model, three slides in your deck and your sales velocity metrics need to reflect that change. You can’t fake that synchronization.
The second thing founders are unprepared for is the intensity of actual due diligence. During the sprint, we grill them thoroughly. We dissect their financial models, challenge their pitch decks, and ask the exact uncomfortable questions an investor will ask. It’s often during this review and “grilling” phase that the true shift happens. Founders realize which KPIs actually matter and what kind of concrete proof they need to provide so their deck doesn’t look like pure fantasy.
I remember one founder having a complete moment of epiphany during a review session. They looked up and said: “This is just like B2B sales, but to capital providers, and I need to have my arguments and preparation thought through in the exact same way, except with even more detail.” That lightbulb moment is what fundraising readiness is really about: moving from slide design to rigorous business defense.
Investor conversations require founders to communicate their business model and financials with real confidence. Where in the sprint do you most often see founders shift from “pitching” to actually defending their economics?
That transformation almost always happens during our financial plan review sessions, when we pull back the curtain and dig into the logic of their bottom-up driver model.
Before this point, many founders view financial models as an uncomfortable requirement, something you put together because investors expect a 5-year hockey-stick chart. But in the review sessions, we look closely at why a financial model might feel unattractive or unconvincing to an investor, and what needs to be fixed to build real credibility.
We roll up our sleeves and analyze the underlying mechanics:
Cash Flow & Working Capital
For physical product or hardware businesses, we map out the exact cash cycle conditions, showing how inventory prepayments or long payment terms impact cash flow long before revenue hits.
Customer Acquisition Cost (CAC) & Sales Cycles
We restructure how they calculate CAC and look honestly at their sales velocity rather than assuming unrealistically low acquisition costs.
Gross Margin Evolution
We map out how margins move over time as volume increases, moving from early-stage inefficiency to operational scale.
When you ground the discussion in unit economics and bottom-up driver planning, something remarkable happens: the confidence click. Suddenly, a revenue figure like €9 million in Year 3 isn’t just an arbitrary target plucked from thin air. We jointly understand the exact operational inputs, customer volume, conversion rates, and sales capacity required to generate that number.
The final step in that session is distilling that dynamic financial model into a clean, 1-page executive summary for their pitch deck. When a founder sees their entire operational strategy mapped out cleanly in numbers, and knows precisely what stands behind every single figure on that slide, they stop guessing. That is the exact moment they get comfortable, because they aren’t memorizing a pitch anymore; they are explaining their business machine.
After the sprint, founders should be able to approach the right investors in a targeted way. How do you help them figure out which investors are actually right for them, and what does a smart outreach strategy look like versus a scattershot one?
We teach founders to approach investor qualification with the exact same discipline as customer qualification. Just like you define an Ideal Customer Profile (ICP), you need an Ideal Investor Profile.
During the sprint, we don’t let founders simply pull a generic directory of venture funds. We build a ranked target list of 40+ deeply researched investors scored against what actually matters to that specific startup, whether that’s a strong B2B sales network in a target geography, access to follow-on round leads, or deep domain expertise. That entire long-list is then plugged directly into a CRM so founders can manage it like a professional sales pipeline.
When it comes to outreach execution, the biggest contrast between amateurs and professionals is discipline and packaging. The single most common mistake in cold outreach is writing endless, philosophical essays that contain virtually zero hard facts. Investors scan; they don’t read essays. Your outreach has to lead with tangible data: clear traction numbers, demonstrable value delivered to customers, and crisp answers to why now and why us.
Crucially, founders often under-leverage warm introductions before hitting “send” on a cold email. You should always exhaust second-degree connections first.
Finally, a smart outreach strategy is never an all-at-once blast. If you email 50 investors in an afternoon, you run the risk of burning through your best leads before getting market feedback. Instead, we train founders to launch in weekly batches of roughly 10 investors. This phased rollout allows you to test messaging, spot recurring questions or objections, and refine your pitch deck and narrative with real market feedback before speaking to your highest-priority targets.
If a founder is 6-12 months away from wanting to raise a round, what are the top three things they should be doing right now to prepare, before they talk to a single investor?
If you’re six to twelve months out, you have a golden window to build leverage. My top three pieces of advice are:
Build a “Proof of Execution” Track Record
This is by far the highest-leverage thing you can do. Investors invest in lines, not dots. Six to twelve months before launching a formal fundraise, start sending concise, bi-monthly updates to a targeted list of prospective investors, with absolutely no ask attached. Simply share what you committed to doing two months ago, what you achieved, and what you plan to tackle next.
We had a cybersecurity startup in our cohort that did this consistently: by the time they officially opened their funding round, over 60% of their target investor list was already thoroughly warmed up. The investors had already watched them hit milestones for months. It drastically shortened their active outreach window and compressed deal cycles because diligence on founder reliability was essentially done.
Fix Housekeeping, Cap Table, and IP Early
Legal debt kills deal velocity faster than almost anything else. Ensure your cap table is clean, make sure all founder and contractor IP assignments are executed and ironclad, and separate personal and company finances completely. If an investor issues a term sheet and finds conflicting founder equity agreements or missing software ownership rights during confirmatory diligence, terms will change, or the deal will evaporate entirely.
Implement Clean Operational and Unit Metric Logging
Don’t wait until round preparation to figure out your customer retention, cohort behavior, CAC, or sales cycle velocity. Implement clean logging now. Having eight months of clean, verifiable historical operational data immediately signals to an investor that you run your startup by the numbers, separating you from 90% of early-stage pitches that rely on unproven forward projections.
The Takeaway: Readiness Is Built, Not Performed
What Petra’s answers make clear is that investor readiness is not a presentation skill. It is the byproduct of a financial model, a pitch narrative, and an operational track record that all tell the same story under pressure. For accelerators, the pattern in this sprint is a useful diagnostic for your own cohorts: founders who enter this kind of process hoping to polish a deck tend to leave with a business they can defend line by line, a targeted investor list built with the same rigor as a sales pipeline, and a track record that starts compounding months before the first investor conversation.